Professionals Insurance Online :: News
SHARE

Share this news item!

David Jones Fallout Shows Why Supplier Credit Risk Matters

The department store’s restructure is a reminder that retail risk can sit beyond the shopfront

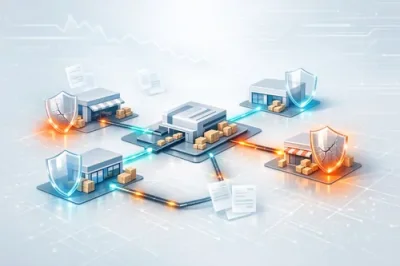
David Jones Fallout Shows Why Supplier Credit Risk Matters?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

David Jones’ move into voluntary administration on 5 November 2026, followed by confirmation that 19 of its 38 stores are set to close, has turned a retail restructuring into a wider lesson about supplier risk.
For Australian retailers, wholesalers and product brands, the issue is not only whether a famous department store survives, but how unpaid invoices, stock ownership and customer concentration can affect cash flow when a major trading partner falters.

McGrathNicol was appointed as voluntary administrator and FTI Consulting as receiver and manager, with the business continuing to trade while a restructure or sale is explored. Media reports have since highlighted suppliers facing delayed payments, unclear recovery prospects and difficult decisions about whether to keep supplying stock. Insurance industry reporting has also pointed to trade credit underwriters reducing or withdrawing cover for goods bound for David Jones months before the formal appointment of administrators.

That distinction is important. Trade credit insurance is not the same as ordinary shop insurance cover. A retail business policy may focus on property, stock damage, theft, liability, glass, equipment breakdown or business interruption after an insured event. Trade credit cover is aimed at the risk that a business customer does not pay for goods or services supplied on credit. For brands that sell through larger retailers, marketplaces, franchise networks or wholesale accounts, that debtor exposure can be as material as the stock sitting on shelves.

The David Jones situation also shows why risk signals matter before a collapse becomes public. Longer payment cycles, requests to change terms, reduced insurer limits, cash-on-delivery demands and unusual silence from finance teams can all indicate that a trading relationship needs closer scrutiny. None of those signs proves a customer will fail, and withdrawing supply can be commercially difficult, especially before Christmas. But ignoring them may leave a smaller supplier carrying unsecured debt at the worst possible time.

Retail operators may wish to consider several practical questions:

  • How much revenue depends on one large customer, landlord, marketplace or distribution channel?
  • Are payment terms, retention-of-title clauses and stock ownership arrangements documented and understood?
  • Does any insurance held respond to debtor default, or only to physical loss and liability events?

There are limits to what insurance can solve. Cover availability, buyer limits, exclusions, notification deadlines and recovery obligations vary, and some businesses may decide to manage credit risk through tighter terms rather than a policy. However, the central message is clear: retail resilience is not just about protecting premises and inventory. It also depends on knowing who owes money, how quickly they pay, and what happens if they cannot.

Published:Thursday, 12th Nov 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

NHVR Prohibition Notice Puts Fleet Systems Under the Insurance Microscope
12 Nov 2026: Paige Estritori
A fresh National Heavy Vehicle Regulator action against a heavy vehicle operator is a timely reminder that insurance risk is not limited to what happens at the moment of a crash. The NHVR announced on 30 October 2026 that it had issued a prohibition notice after identifying significant and ongoing safety risks, including repeated defects in safety-critical systems and concerns about the operator’s management controls. - read more
Diagnosis timing is not the only test for income cover
12 Nov 2026: Paige Estritori
A recent income protection dispute has put fresh attention on a difficult but important issue for Australian workers: a medical condition may be treated as pre-existing even where a formal diagnosis comes later. The case, reported on 9 November 2026, involved a prostate cancer claim that was declined after the Australian Financial Complaints Authority accepted that earlier medical warning signs and specialist investigations were enough to trigger a pre-existing condition exclusion. - read more
Fuel Recovery Order Restarts, Raising Insurance Budget Questions
12 Nov 2026: Paige Estritori
The Fair Work Commission’s varied fuel cost recovery order will restart obligations from 23 November 2026, requiring covered road transport contractual chains to account for higher fuel costs against the 6 March 2026 benchmark. For truck operators, the immediate issue is contract pricing, but the insurance angle is also important: cash flow, route choices, subcontracting arrangements and vehicle utilisation all influence how risk is presented and managed. - read more
Court Ruling Highlights Why TPD Wording Matters for Business Owners
12 Nov 2026: Paige Estritori
A Queensland Court of Appeal decision involving AIA Australia has put renewed attention on how technical policy conditions can affect total and permanent disability claims, and why business owners should not treat insurance wording as a background detail. The case concerned group TPD cover held through superannuation, but its broader message is relevant to SMEs that rely on life, TPD and disability-style cover to protect debt, ownership arrangements and business continuity. - read more
Latest Claims Data Shows Why Policy Structure Still Matters
12 Nov 2026: Paige Estritori
APRA’s latest life insurance claims and disputes statistics, released on 16 October 2026 and covering the 12 months to 30 June 2026, provide a useful reminder for Australian businesses: the practical value of cover often depends on how clearly it is structured, documented and understood before a claim ever arises. - read more


Professionals Insurance Articles

Protecting Your Professional Income: Understanding Income Protection Insurance
Income protection insurance is a financial safety net for individuals who are unable to work due to illness or injury. It ensures that you receive a percentage of your income during times when you cannot earn a salary, helping you maintain your lifestyle as you recover. This type of insurance offers peace of mind by providing financial support when it is needed most, allowing you to focus on recovery rather than financial pressures. - read more
How Policy Limits, Sums Insured and Excesses Work in Professional Insurance
Policy limits, sums insured, sub-limits and excesses affect how much an insurer may pay and how much a professional business may need to contribute if a claim is accepted. Understanding these terms can help Australian professionals compare quotes and policy documents more confidently. - read more
When Are Australian Professionals Required to Hold Insurance?
Australian professionals may need insurance because of laws, licensing rules, professional body standards, client contracts, leases, tenders or operational risks. This guide explains the main sources of insurance obligations and what to check before accepting work. - read more
What Is Packaged Insurance for Professionals?
Packaged insurance for professionals brings several business insurance covers into a coordinated arrangement, helping consultants, contractors and small professional firms review their risks in one place rather than managing every policy separately. - read more
Tailoring Income Protection for Medical Professionals
Income protection insurance is a vital safety net for individuals across various professions, designed to provide financial stability if one is unable to work due to illness or injury. This type of insurance replaces a percentage of your income, alleviating the burden of regular expenses while you focus on recovery. For medical professionals who often have high earnings and extensive financial commitments, this coverage is particularly important. - read more

Knowledgebase
Insurance Premium:
The periodic amount paid for the purchase of insurance.