Storm Claims Highlight Cover Gaps for Home Service Operators
Severe weather response shows why mobile and home-based businesses need clear records, limits and claim plans
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
The Insurance Council of Australia’s Significant Event declaration for severe storms affecting Queensland and parts of New South Wales since 11 November 2026 is a timely warning for domestic and home service businesses.
By 16 November, insurers had received 4,670 claims, mainly for fallen trees and branches, damaged roofs and fences, and water entering homes.
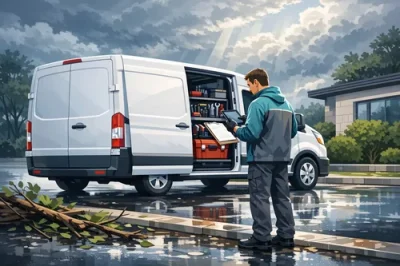
While most of those claims will be household-focused, the same weather can quickly disrupt cleaners, gardeners, maintenance providers, mobile technicians and other operators who depend on safe access to clients’ properties.
The immediate insurance issue is not only whether a business premises has been damaged. Many home service operators work from a residence, store tools in vehicles or garages, rely on booking software, and move between suburbs where roads, power and customer availability can change by the hour. A storm can therefore create several exposures at once: damaged equipment, cancelled jobs, unsafe work sites, delayed staff movements and disputes about who is responsible for damage that occurs during clean-up or repair work.
For small operators, the practical lesson is to separate household insurance from business risk. A standard home policy may not automatically cover business stock, specialist tools, client property exposure or income lost after an interruption. Likewise, commercial policies can include limits, exclusions, excesses and evidence requirements that only become obvious during a claim. Operators who keep tools at home or in a vehicle should check whether cover applies at those locations, in transit, overnight and during severe weather.
Storm recovery also brings liability risks. A gardener clearing branches, a cleaner entering a water-damaged home or a handyman completing urgent make-safe work may be operating in conditions that are very different from a routine appointment. That makes safe work procedures, photographs, job notes and clear client instructions important. Where work involves accidental injury or property damage exposure, public liability insurance may be relevant, but it still needs to match the actual services performed.
Business continuity deserves equal attention. Even when tools and vehicles are undamaged, operators may lose work if clients postpone visits, local roads are closed or power-dependent services cannot proceed. Some policies may include business interruption cover, but triggers and waiting periods vary. A short outage, for example, may not be treated the same way as physical damage to insured property.
Before the next severe weather warning, home service businesses can use this event as a checklist prompt:
confirm where tools, equipment and supplies are covered;
review whether home-based business activities have been disclosed;
keep receipts, serial numbers, photos and maintenance records;
document cancellations, access problems and storm-related costs;
avoid starting urgent work where site safety is unclear.
The Significant Event declaration should help insurers coordinate their response, but it does not remove the need for policyholders to prove loss and meet policy terms. For domestic service operators, preparation remains the difference between having insurance in place and being genuinely claim-ready.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
A NSW parliamentary inquiry into the state of live music has put public liability insurance back in the spotlight for venues, festivals and event operators, after its final report identified insurance affordability as a significant operating pressure and recommended further work on reform options. - read more
A NSW parliamentary inquiry into the state of live music has put insurance affordability back in the spotlight, with its final report tabled on 9 November 2026 identifying public liability insurance as a major cost burden for venues and festivals. The recommendation does not change premiums immediately, but it gives business owners a useful signal: governments, insurers and industry groups are still grappling with how public-facing risks are priced, documented and managed. - read more
The Insurance Council of Australia’s expanded Significant Event declaration for severe storms in Queensland and New South Wales is a timely reminder that insurance is tested in the messy aftermath of damage, power loss and disruption, not just at renewal time. By 17 November 2026, insurers had received more than 7,500 claims linked to severe weather from 11 to 17 November, with damage ranging from torn roofs and broken fences to water entry, hail impacts and spoiled food after outages. - read more
A recent business interruption dispute involving a bakery has given restaurant and cafe operators a timely reminder that disruption does not always start inside the insured premises. The Australian Financial Complaints Authority found in favour of a bakery retail business after its insurer declined a claim linked to a fire at the premises of its sole supplier, bringing supplier-dependency wording into sharp focus for hospitality businesses that rely on specialist producers, central kitchens, roasters, wholesalers or delivery partners. - read more
The National Heavy Vehicle Regulator’s 16 November 2026 warning to put safety ahead of freight deadlines is more than a seasonal road-safety message. For transport operators, the Black Friday and pre-Christmas delivery rush is also a live risk-management test, with driver fatigue, vehicle checks, scheduling pressure and Chain of Responsibility duties all capable of influencing claims, liability exposure and future truck insurance discussions. - read more
Businesses operate in a wide variety of industries and each faces a different combination of financial, operational, legal and physical risks. Business insurance encompasses a broad range of insurance products designed to respond to different types of insured events, helping businesses manage financial exposures arising from their day-to-day activities. - read more
Risk assessment in insurance is the process of identifying, analysing and evaluating the exposures that may result in an insured event or financial loss. For professionals and businesses, this assessment considers the nature of the services provided, the operating environment, contractual obligations, regulatory requirements and other factors that may influence the likelihood or potential cost of future claims. - read more
Packaged insurance for professionals brings several business insurance covers into a coordinated arrangement, helping consultants, contractors and small professional firms review their risks in one place rather than managing every policy separately. - read more
In our digitally-driven world, cyber insurance has become an essential safeguard for anyone who operates online, particularly freelance professionals. At its core, cyber insurance is designed to help cover the risks associated with cyberattacks or data breaches, which can be devastating to both your reputation and your finances. - read more
Policy limits, sums insured, sub-limits and excesses affect how much an insurer may pay and how much a professional business may need to contribute if a claim is accepted. Understanding these terms can help Australian professionals compare quotes and policy documents more confidently. - read more
Knowledgebase
Moral Hazard: The concept that individuals may take on more risk when they do not bear the full consequences of that risk, often relevant in insurance scenarios.


No comments yet. Be the first to share your thoughts.